Maybe you’ve driven through downtown Waukesha, walked along the Fox River, and thought, “I could see myself here.” That feeling — equal parts excited and nervous — is exactly where most first-time buyers start, and getting from there to the keys is more reachable than it looks.
I’m Adam Zeman, a licensed loan officer with 15+ years in Wisconsin mortgages, working just down the road in Wauwatosa. Let me walk you through buying a home in Waukesha as a first-time buyer — the money, the steps, and where a local lender genuinely helps — in plain dollars.
What do you need for buying a home in Waukesha?
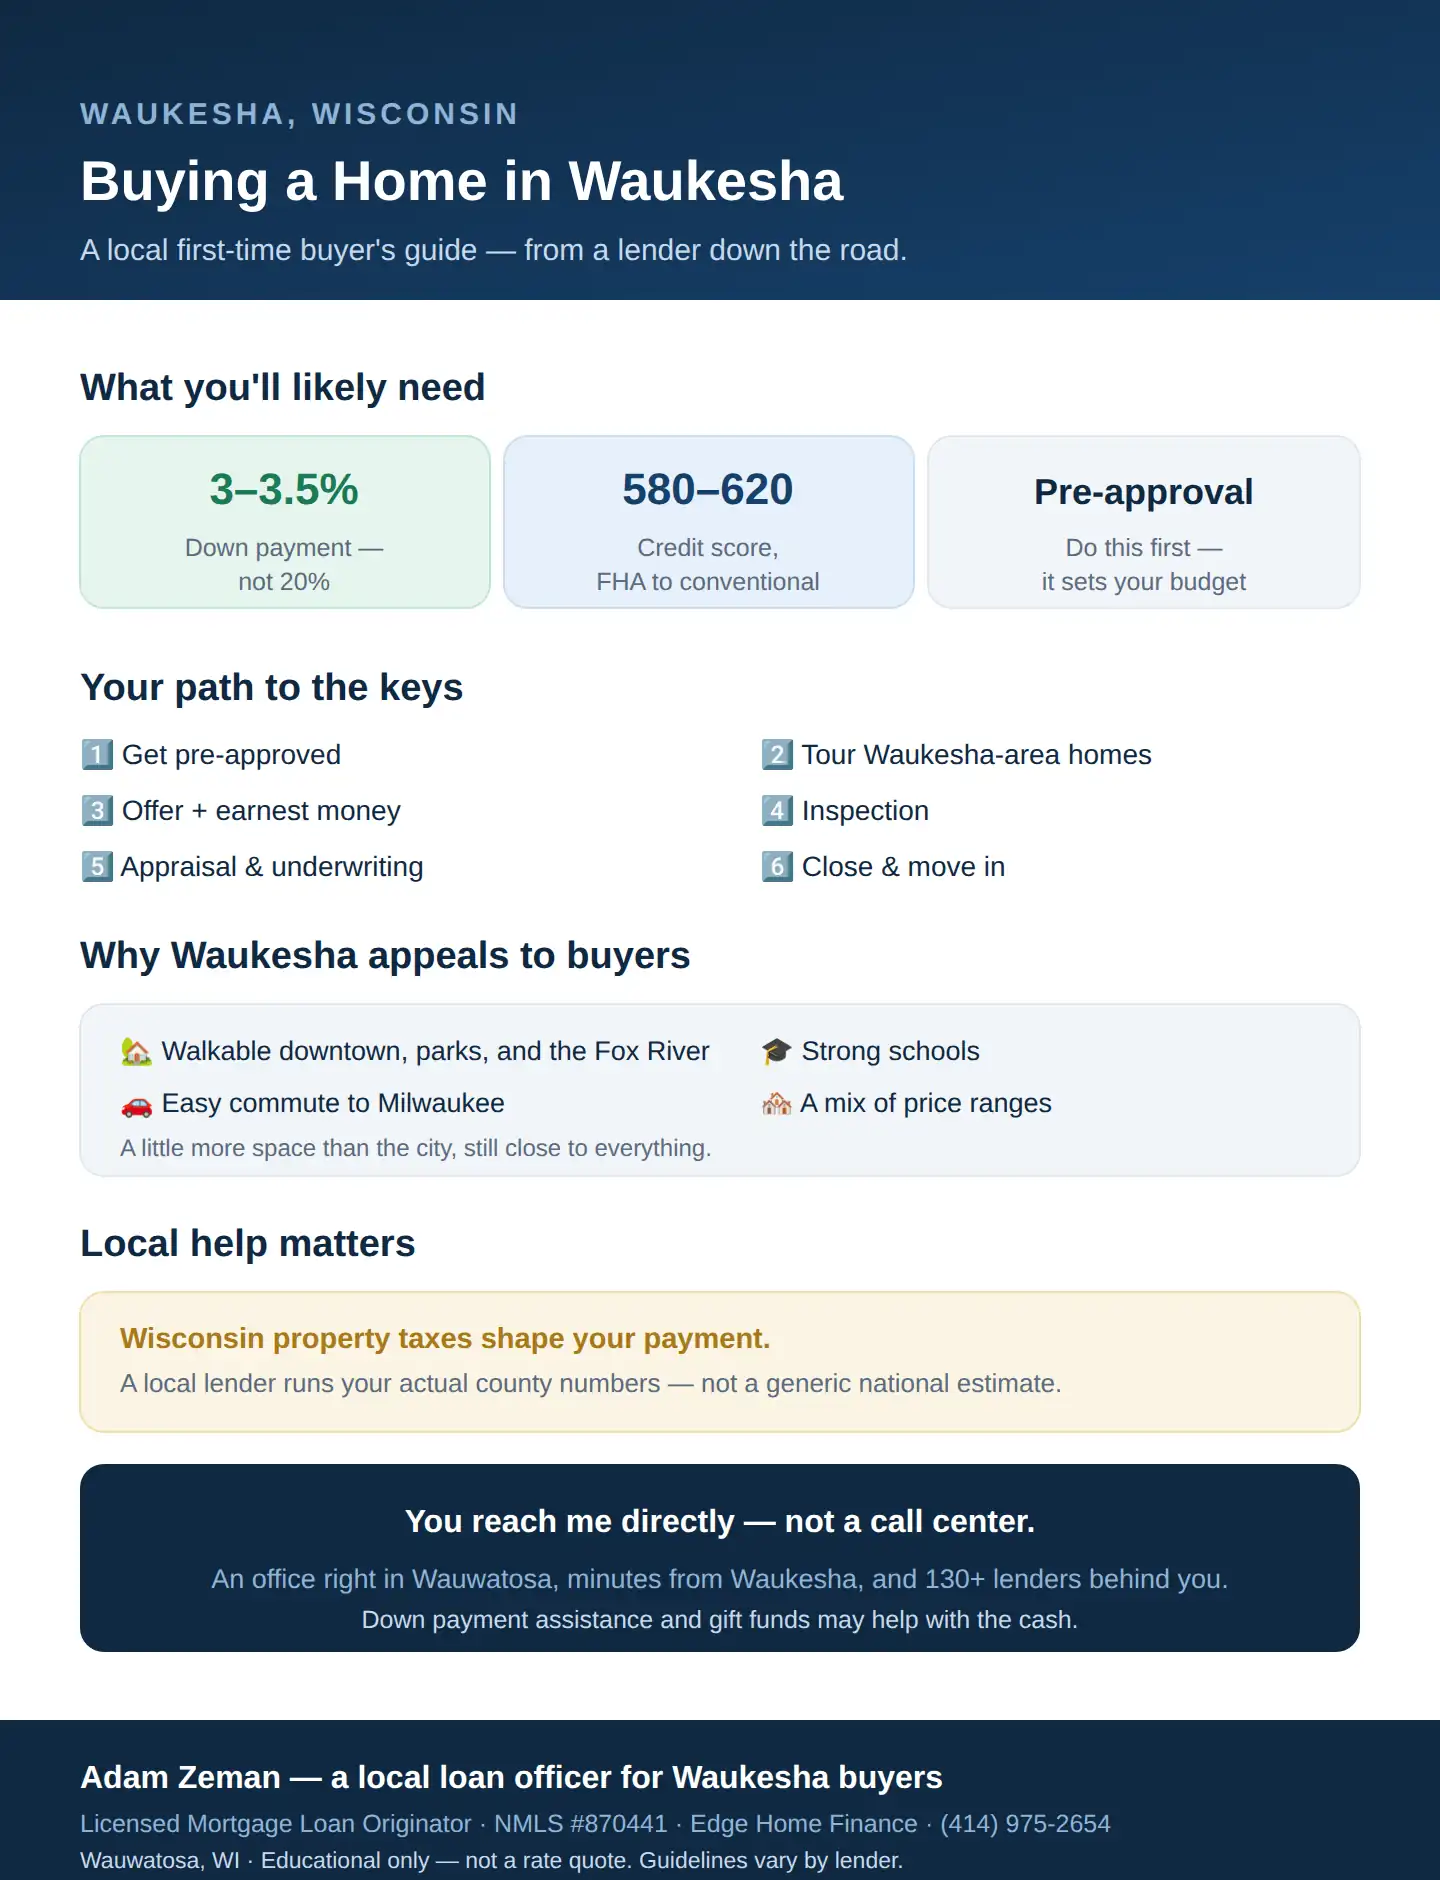
In short, three things: a down payment, a credit score that clears your loan’s floor, and steady income. The reassuring part is that each bar is lower than most first-timers assume. Here’s the quick picture before the details.
| What you need | Typical starting point |
|---|---|
| Down payment | 3% (conventional) to 3.5% (FHA) |
| Credit score | Around 580 (FHA) to 620 (conventional) |
| Income | Steady, usually a two-year history |
| Closing costs | Roughly 2%–5% (sometimes seller-paid) |
How much down payment do you really need?
Less than you think when buying a home in Waukesha. First-time buyers can put down as little as 3% on a conventional loan or 3.5% on FHA. On a $300,000 Waukesha home, that’s $9,000 to $10,500 — a long way from the $60,000 a 20% down payment would demand.
Better still, your down payment can often come from a gift from family, and many Wisconsin buyers qualify for down payment assistance. So the upfront cash is usually the smallest hurdle, not the biggest.
What are the steps to buying a home in Waukesha?
The process feels big until you break it into steps. Here’s the path most local first-time buyers follow, start to finish.
- Get pre-approved — this sets your budget and shows sellers you’re serious.
- Tour Waukesha-area homes in your price range with an agent.
- Make an offer and put down earnest money.
- Get a home inspection so there are no surprises.
- Let the loan process through appraisal and underwriting.
- Close, get the keys, and move in.
So notice pre-approval comes first, before you fall for a house. That order keeps you shopping in the right range and makes your offer competitive.
Why do buyers love Waukesha?
Part of the appeal of buying a home in Waukesha is the mix it offers: a walkable, historic downtown, parks and the Fox River, solid schools, and an easy commute into Milwaukee. You get a little more space than the city without giving up being close to everything. And with a range of price points, there’s often something that fits a first-time budget.
So it’s a popular landing spot for buyers who want community and value in one place.
Why does a local lender matter when buying a home in Waukesha?
Because Wisconsin property taxes are a real part of your payment, and they vary by community. A local lender runs your actual Waukesha County numbers rather than a generic national estimate, so the payment you plan around is the real one. Beyond that, you reach me directly — not a call center — and I shop your loan across 130+ lenders. If you want the statewide overview, see my first-time home buyer guide.
How do you start buying a home in Waukesha?
The honest answer is that it starts with a short conversation, not a house. Because your budget, loan type, and down payment all depend on your specific numbers, the smartest first step is a pre-approval that maps it out. That’s what I do — I look at your real situation and shop it across 130+ lenders so you start with the strongest terms.
Frequently asked questions
How much do I need for buying a home in Waukesha?
Often just 3%–3.5% down plus closing costs. On a $300,000 home, that can be around $9,000–$10,500 down, sometimes less with gifts or seller credits.
What credit score do I need?
Around 580 for FHA or 620 for conventional. A higher score earns a lower rate, so it’s worth a little effort first.
Do I need to be a first-time buyer to get help?
Not always. Many low-down-payment loans are open to anyone, though some assistance programs are reserved for first-time buyers.
Can my down payment be a gift?
In most cases, yes. A gift from a family member is a common, fully allowed way to fund the down payment.
How long does buying take?
Commonly 30 to 45 days from accepted offer to closing, though pre-approval keeps things moving.
Are Waukesha property taxes high?
Wisconsin taxes are on the higher side and vary by community, so I build your real numbers into the plan.
Should I get pre-approved before touring homes?
Yes, always. It sets your budget and strengthens your offer the moment you find the right place.
Can I buy with student loans?
Often yes. They count in your debt-to-income ratio (DTI) but rarely rule you out by themselves.
Key takeaways
- Buying a home in Waukesha usually needs just 3%–3.5% down, not 20%.
- Credit floors are around 580 (FHA) or 620 (conventional), and a higher score means a lower rate.
- Above all, pre-approval comes first — it sets your budget and strengthens your offer.
- Also look into down payment assistance and gift funds for the upfront cash.
- A local lender runs your real Waukesha County tax numbers, so the payment is accurate.
Ready to start in Waukesha?
Let’s find out what you qualify for — the real number, across 130+ lenders, with no pressure. Grab a 15-minute call on my calendar, or call or text me at (414) 975-2654.
Adam Zeman — Licensed Mortgage Loan Originator, NMLS #870441 — Edge Home Finance, LLC, Company NMLS #891464 — 11220 W Burleigh St, Suite 174, Wauwatosa, WI 53222 — (414) 975-2654 — Book: calendly.com/adam-zeman/30min. Educational information only, not a rate quote or commitment to lend. Loan guidelines, down payment, and credit requirements vary by lender and by borrower. All loans subject to credit approval and underwriting. Equal Housing Opportunity.