Watching credit card minimums eat your paycheck while the balance barely moves is exhausting — and a little scary. If you own a home with equity, there may be a way to break that cycle by putting your low mortgage rate to work against your highest-cost debt.
I’m Adam Zeman, a licensed loan officer with 15+ years in Wisconsin mortgages. Let me walk you through how a cash-out refinance to pay off debt works, run the real numbers, and give you the honest test for whether it’s actually a smart move for you.
How does a cash-out refinance to pay off debt work?
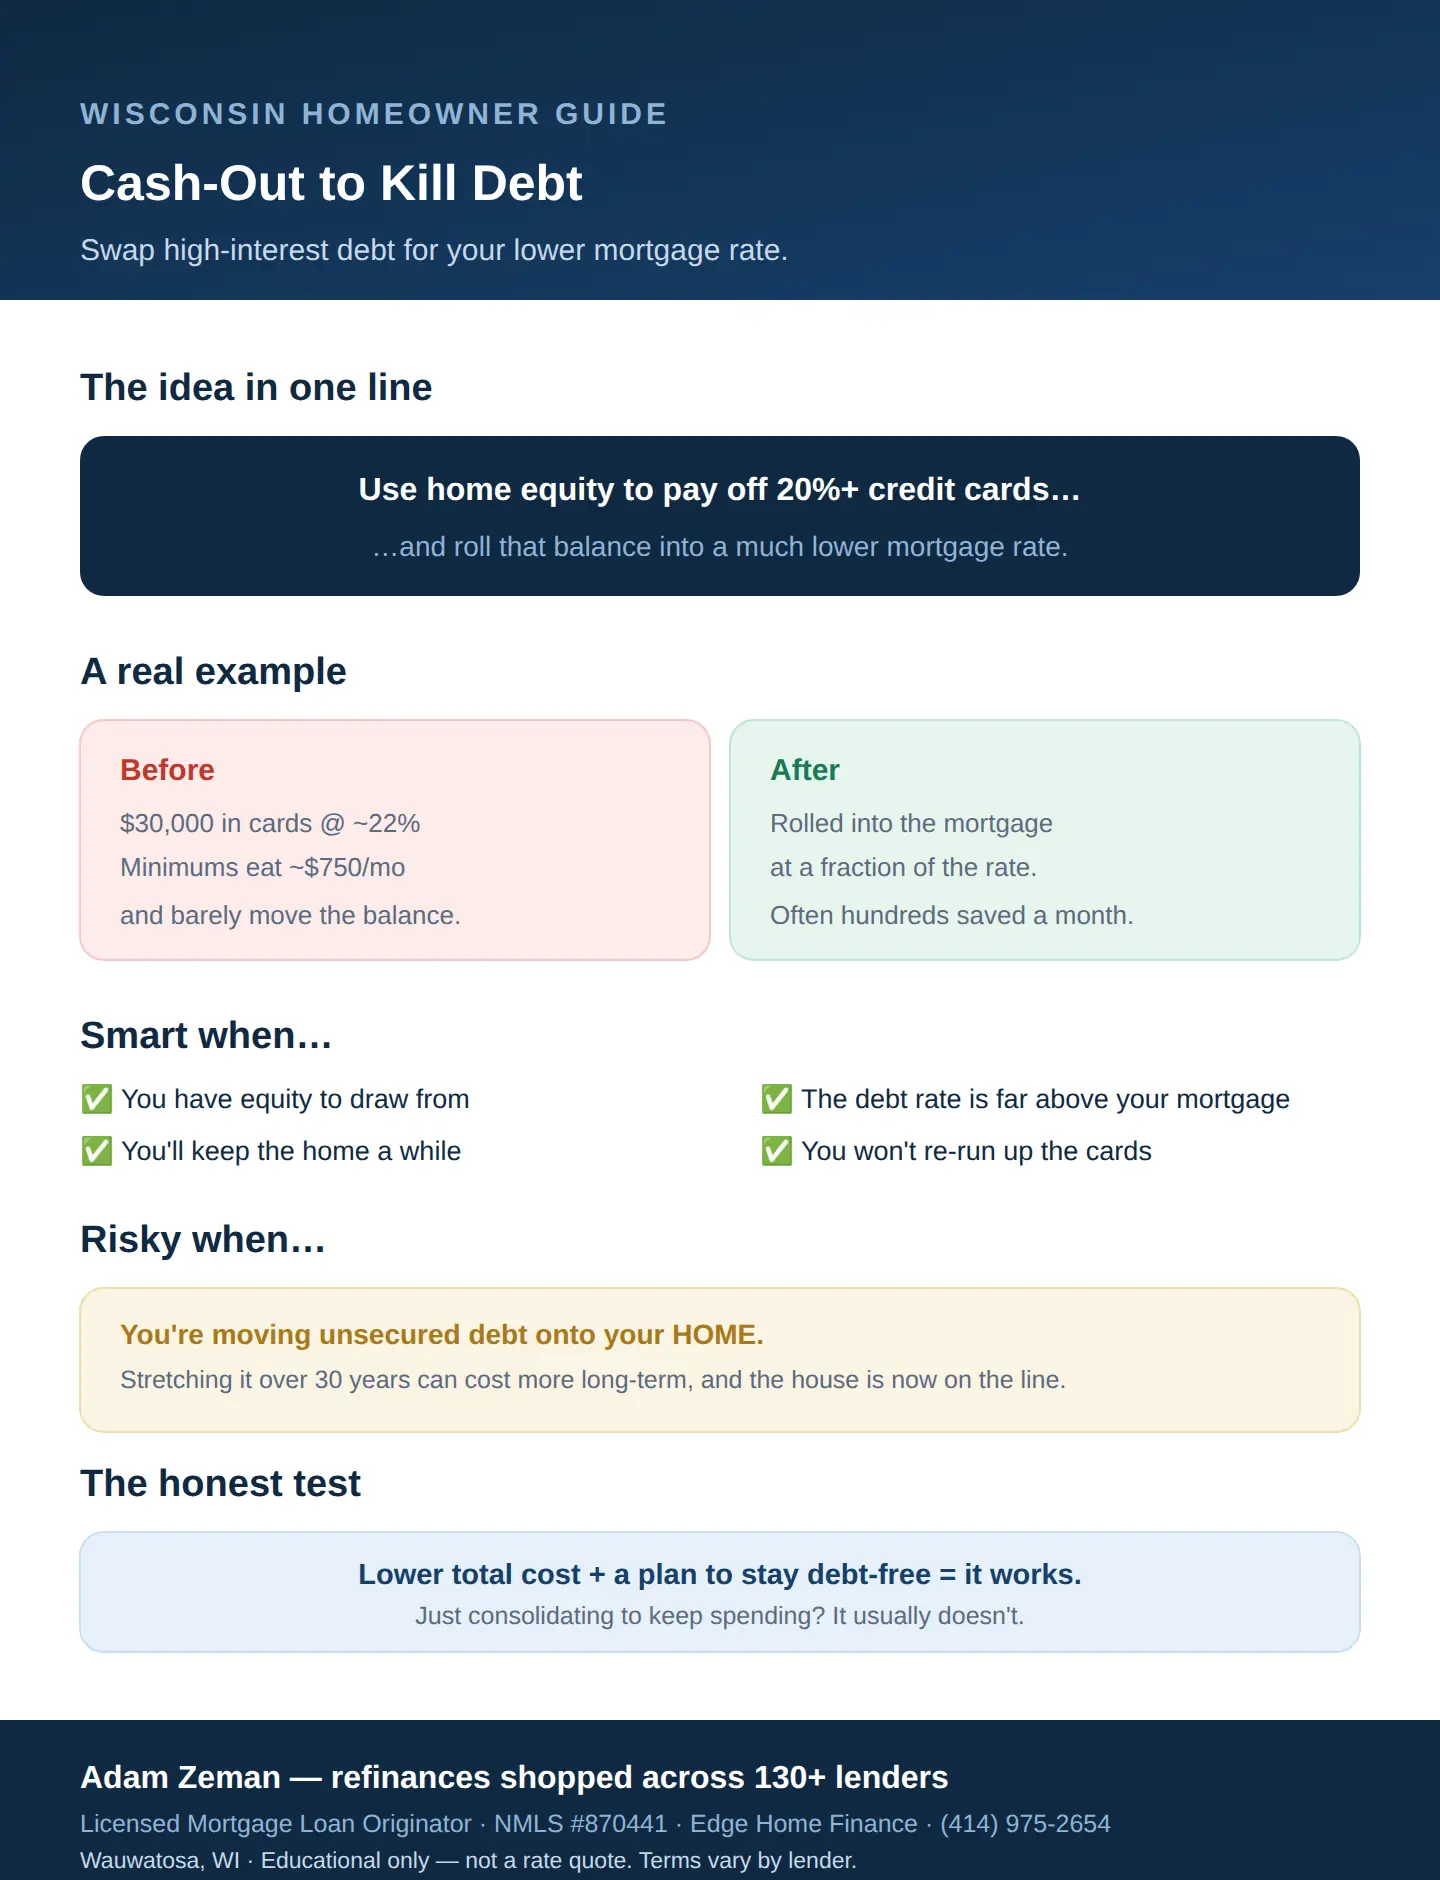
In short, you refinance into a new, larger mortgage and take the extra amount as cash. Then you use that cash to pay off your high-interest balances. Because you’re swapping expensive debt for your much lower mortgage rate, your total interest cost usually drops, and your combined monthly payments often shrink.
So a single balance at a mortgage rate replaces a pile of cards charging 20% or more. That’s the whole appeal — you’re not erasing the debt, you’re moving it somewhere far cheaper.
How much can a cash-out refinance to pay off debt actually save?
Let’s put real numbers on it. Say you carry $30,000 in credit cards at around 22%, with minimums eating roughly $750 a month while the balance barely budges. Roll that $30,000 into your mortgage, and it now carries your mortgage rate instead.
| Credit cards | Rolled into mortgage | |
|---|---|---|
| Rate | ~22% | Your mortgage rate |
| Monthly bite | ~$750 in minimums | Far lower |
| Balance progress | Barely moves | Steadily paid down |
For many homeowners, that swing frees up several hundred dollars a month. So the monthly relief is real — but there’s a catch worth understanding.
Is a cash-out refinance to pay off debt a good idea?
It can be, and it can also backfire, so honesty matters here. The upside is clear: lower interest and lower monthly payments. The risk is that you’re moving unsecured debt onto your home, and stretching it over 30 years could cost more in the long run — plus the house is now on the line if things go sideways.
So the deciding factor is behavior. If you’ll pay it down and not re-run up the cards, it’s often a genuine win. If it’s just a reset to keep spending, it usually isn’t.
When does it make the most sense?
A few conditions make this a clear winner. You have enough equity to draw from, the debt’s rate is far above your mortgage, you plan to keep the home a while, and you’re committed to not rebuilding the balances. When those line up, the math strongly favors the move.
- You have equity, usually leaving 20% in after the cash-out.
- Your debt costs far more than your mortgage rate.
- You’ll stay in the home long enough to benefit.
- You have a real plan to stay out of new debt.
What are the risks to weigh?
Because your home secures the new loan, the stakes are higher than with a card. First, missed payments now threaten the house, not just your credit. Second, spreading a short-term balance over a long mortgage can raise the lifetime interest unless you keep paying extra. So I always show clients both views — the monthly relief and the long-term cost — before anyone commits.
How do I know if it’s right for me in Wisconsin?
The honest answer is that it comes down to your equity, your rates, and your plan. Because lender pricing varies, the same cash-out can look different from one lender to the next — so I shop it across 130+ lenders and run the full math with you. For the bigger picture, see my guide to refinancing in Wisconsin.
Frequently asked questions
Does a cash-out refinance to pay off debt hurt my credit?
Short-term, the credit pull dips your score slightly, but paying off cards can actually help by lowering your utilization.
How much equity do I need?
You can typically borrow up to about 80% of your home’s value, so you’ll want enough equity to cover the debt and still leave a cushion.
Is the interest tax-deductible?
Not usually when the cash pays off personal debt. Check with a tax professional for your situation.
Will my mortgage payment go up?
Your mortgage payment rises since the balance is larger, but your total monthly payments often drop once the cards are gone.
What if I run the cards back up?
Then you’re worse off, with both a bigger mortgage and new card debt. A plan to stay debt-free is essential.
How long does it take?
Commonly 30 to 45 days from application to closing, once your documents are in.
Can I pay off other debt too?
Yes. Car loans, medical bills, or other high-interest balances can be consolidated the same way.
Is a HELOC better than a cash-out refinance?
Sometimes, depending on rates and how much you need. I’ll compare both so you see which is cheaper.
Key takeaways
- A cash-out refinance to pay off debt swaps high-interest balances for your lower mortgage rate.
- On $30,000 of 22% cards, the monthly relief can be several hundred dollars.
- It works when you have equity, you’ll keep the home, and you won’t rebuild the debt.
- Also weigh the risk: unsecured debt is now on your home, and 30 years can add lifetime interest.
- Because pricing varies, shopping the refinance is what turns a maybe into a clear yes or no.
Want to see your real numbers?
Tell me your balances, rates, and equity, and I’ll show you the true before-and-after across 130+ lenders. Grab a 15-minute call on my calendar, or call or text me at (414) 975-2654.
Adam Zeman — Licensed Mortgage Loan Originator, NMLS #870441 — Edge Home Finance, LLC, Company NMLS #891464 — 11220 W Burleigh St, Suite 174, Wauwatosa, WI 53222 — (414) 975-2654 — Book: calendly.com/adam-zeman/30min. Educational information only, not a rate quote, commitment to lend, or tax advice. Refinance rates, equity, and terms vary by lender and by borrower. All loans subject to credit approval and underwriting. Equal Housing Opportunity.