Buying a home in Cedarburg often means buying something older than the state’s plumbing code. That’s the charm, and it’s also the paperwork.
Limestone walls, creek views, a downtown people drive an hour to visit. Then your lender asks about the electrical.
Here’s what an old house actually does to your loan.
What makes Cedarburg’s housing stock different?
Age, and a town that chose to keep it. Buying a home in Cedarburg usually means buying a piece of that decision. Settlers arrived in the 1840s and the city incorporated in 1885.
More than 200 historic buildings have been preserved here. The city holds eight National Register of Historic Places listings, and the Washington Avenue Historic District covers the downtown along Cedar Creek.
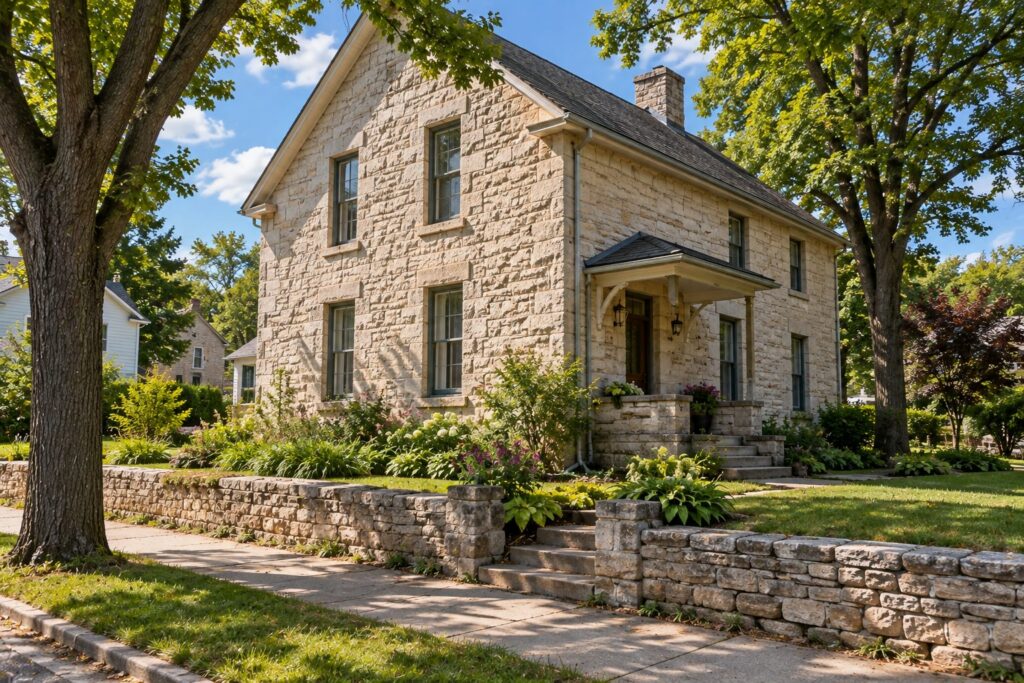
Early settlers built with local limestone, and some mid-19th-century limestone structures are still standing.
Cedarburg had 12,121 residents at the 2020 census across 5,438 housing units. It sits in Ozaukee County, about 20 miles north of Milwaukee.
The woolen mill from 1864 was nearly demolished for a gas station in the 1970s. Somebody pointed out there was no demolition permit to issue. That delay saved the whole district.
Does a historic listing restrict what you can do?
National Register listing on its own does not restrict a private owner. Local rules are a separate question.
That distinction matters and gets muddled constantly. Federal listing is mostly recognition, and it can open doors on certain tax credit programs for qualifying commercial buildings.
Local review is where the actual limits live. So ask the city directly whether the specific address falls under any local design or demolition review.
It’s usually a short answer. It’s also a much better question to ask in week one than in week five, after you’ve chosen windows.
Either way, get the pre-approval built around the real property before you start imagining a kitchen.
What buying a home in Cedarburg does to your appraisal
It makes comparable sales harder to find, and that’s the whole problem.
An appraiser values your house against recent sales of similar homes. A limestone cottage from the 1860s doesn’t have many similar homes, and the ones it does have may not have sold recently.
Fewer comps means bigger adjustments. Bigger adjustments mean the final number has more room to wander.
So build in a little margin when you’re buying a home in Cedarburg at the top of your budget. An appraisal that lands under contract price is a cash problem, and it’s yours to solve.
Financing the work when buying a home in Cedarburg
A renovation mortgage lets you borrow for the purchase and the repairs together, in one loan.
Fannie Mae’s HomeStyle Renovation product is the common conventional route. There’s no minimum dollar amount and no list of restricted improvement types, which is unusually flexible.
Improvements generally have to be permanently affixed to the property. Certain appliances installed during a kitchen or utility room remodel are the exception.
It also covers outdoor buildings and structures. Accessory units, garages, recreation rooms and swimming pools all qualify where local zoning allows and building codes are met.
That last clause is doing real work in a historic district. Zoning first, then the pool.
The 15-month clock on renovation work
Renovation work has to be finished within 15 months of your loan closing.
For rare projects that run longer, the lender has to escalate it to Fannie Mae, which decides the remedy. The options include an extension to 18 months from closing, cutting the scope back, or repurchase.
Fifteen months sounds like plenty. Then you open a wall in a house built in 1870 and discover why the floor slopes.
Pad the schedule. Contractors who work on old buildings will tell you the same thing, usually while shaking their head at something.
And while you’re budgeting, keep the total honest, because renovation costs are famously optimistic on paper.
What a renovation loan can’t do
It can’t fund a complete tear-down and reconstruction. That’s the hard line.
You can renovate extensively. You cannot level the building and start again on the same loan. In a city with 200-plus preserved historic buildings, that’s rarely the plan anyway.
There’s one more useful case. A HomeStyle loan can finish a newly built home that’s at least 90% complete, limited to non-structural items the builder left undone.
Also worth knowing: servicing can’t transfer during the renovation period. Your loan stays put until the work is signed off.
Insurance and inspection, before you waive anything
Call an insurance agent before your inspection contingency expires. Not after. This is the step people skip when buying a home in Cedarburg.
Older electrical, older plumbing and older roofs can all affect what an insurer will write and what they’ll charge. That answer belongs in your budget, not in a surprise email in week six.
Hire an inspector who actually works on pre-1900 buildings. A good one reads a stone foundation differently than a 1990s poured basement, because it is different.
Ask specifically about the systems you can’t see. Knob-and-tube wiring, galvanised supply lines, and whatever is going on under the porch.
When buying a home in Cedarburg isn’t the right call
When you want the look of an old house without the ownership of one.
Let me argue against my own file here. An 1870s limestone house is a commitment. It’ll need specialists, it’ll cost more to heat, and parts of it will never be square again.
Say what you actually love is the downtown and the festivals. You can have both from a 1995 colonial two miles out, with a furnace made this century.
Buy the old house because you want to be its caretaker. That’s a real and good reason. Just go in with your eyes open and a loan that fits the plan.
Frequently asked questions about buying a home in Cedarburg
Does National Register listing stop me renovating?
Not by itself. Federal listing doesn’t restrict private owners, but local review may apply, so ask the city about the specific address.
How long do I have to finish renovation work?
Fifteen months from closing on a HomeStyle Renovation loan, with a possible extension to 18 months through Fannie Mae.
Can I tear the house down and rebuild?
Not with a HomeStyle Renovation loan. Complete tear-down and reconstruction is excluded.
Is there a minimum renovation amount?
No. Fannie Mae sets no minimum dollar amount and no restricted improvement types.
Can I add a garage or a pool?
Yes, where local zoning allows and building codes are met. Outdoor buildings and structures are covered.
Why is the appraisal harder on an old house?
Unique historic homes have fewer comparable sales, which means larger adjustments and a less predictable final value.
Key takeaways on buying a home in Cedarburg
- Cedarburg has more than 200 preserved historic buildings and eight National Register listings.
- The city had 12,121 residents and 5,438 housing units at the 2020 census.
- National Register listing alone doesn’t restrict private owners; local review is a separate question.
- Unique older homes have fewer comparable sales, so appraised values are less predictable.
- HomeStyle Renovation has no minimum amount and no restricted improvement types.
- Renovation work must finish within 15 months of closing, extendable to 18 in rare cases.
- A renovation loan can’t fund a complete tear-down and reconstruction.
Talk through your options with a local loan officer
Found an old Cedarburg house that needs work?
Send me the address and a rough scope. I’ll show you what a renovation loan would cover, what the 15-month clock means for your contractor’s schedule, and what the appraisal is likely to do with a one-of-a-kind house. You’ll know the real all-in number before you write the offer. You reach me directly — I answer my own phone.
Call or text me:
Adam Zeman : Edge Home Finance
I’m Adam Zeman — a Wisconsin loan officer who’d rather talk you out of the wrong loan than close it. I answer my own phone.
Senior Loan Originator · NMLS #870441
Edge Home Finance, LLC · NMLS #891464 · Licensed in Wisconsin
📞 (414) 975-2654 · azeman@edgehomefinance.com · adamzmortgageteam.com
YouTube: @Adamzmortgageteam · Reddit: u/azem4356
Read this next: How renovation loans work in Wisconsin
Educational only — not a rate quote. Agency renovation and appraisal guidance changes; the Fannie Mae requirements cited here come from the Selling Guide and should be confirmed as current. Historic designations, local review and zoning vary by property and municipality; confirm with the City of Cedarburg. Census figures carry their date. Qualifying guidelines vary by lender, program and borrower, and not all borrowers or properties will qualify. Edge Home Finance, LLC is a private broker, not affiliated with HUD, the FHA, or any government agency.
Edge Home Finance, LLC · NMLS #891464 · Licensed in Wisconsin