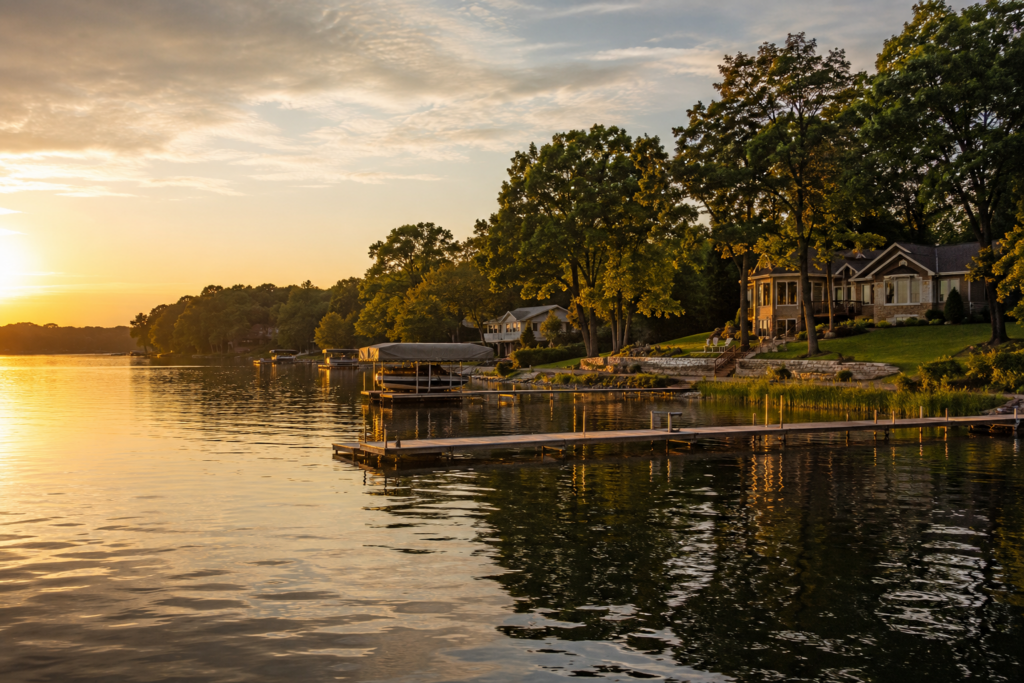
Lake Country is where Milwaukee goes when it wants a pier. Buying a home here is a little different from the rest of the metro — and worth understanding before you fall for a place on the water.
Buying a home in Lake Country means competing in one of the priciest, fastest-moving corners of Waukesha County. Prices run high, lakefront runs higher, and the winning offer usually isn’t the biggest one — it’s the best-prepared one. Here’s how the market and the financing actually work.
Where is Lake Country, Wisconsin?
Lake Country is the cluster of lake communities in western Waukesha County, about 30 minutes west of Milwaukee.
It covers Oconomowoc, Delafield, Hartland, Pewaukee, Nashotah, Chenequa, and Merton, wrapped around a chain of glacial lakes — Pewaukee, Nagawicka, Oconomowoc, Okauchee, Pine, and Lac La Belle. Big water, good schools, and a short drive to both Milwaukee and Madison.
What does it cost to buy a home in Lake Country?
More than most of the metro — this is some of the highest-value real estate in the Milwaukee area.
Inland homes are one price. Anything with lake access or lakefront is another entirely, and the premium can be large. The practical effect for your loan: plenty of Lake Country homes push past the conforming loan limit, which tips you out of a standard mortgage and into a jumbo loan.
That’s not a problem — it just changes the playbook. If you’re weighing a home up here, it’s worth getting pre-approved for a real number before you tour, so you know where you stand.
What loans work best for a Lake Country home?
It depends on the price and the property.
- Conventional — the workhorse for homes under the conforming limit, with as little as 5% down.
- Jumbo — for higher-priced and most lakefront homes above the conforming limit. Expect a larger down payment and tighter credit and reserve requirements.
- Second-home financing — if that lake place is a weekend home, not your primary. The terms differ, so say so up front.
- Construction / one-time close — if you’re building on a lot rather than buying existing.
Educational only — not a rate quote. Down-payment and program guidelines vary by lender and by borrower, mortgage insurance may apply, and not all borrowers will qualify. Edge Home Finance, LLC is a private broker, not affiliated with HUD, the FHA, or any government agency.
Why pre-approval matters more in Lake Country
Good homes here don’t sit. A well-priced place on the water can draw multiple offers in a weekend.
In that market, your loan is your edge. A strong, verified pre-approval tells the listing agent you’ll actually close — and that calm confidence often beats a slightly higher offer from a shakier buyer. The one who wins usually isn’t the richest; it’s the one whose financing doesn’t make anyone nervous.
Want that edge before you’re up against a deadline? Let’s build your pre-approval so you can move the day the right place hits.
What about property taxes and lake homes?
Two things to plan for up here.
Wisconsin property taxes are a real line in your monthly payment, and lakefront assessments tend to run higher than inland. That flows straight into your escrow, so the payment on a lake home is more than just principal and interest. A local lender runs your actual community’s numbers instead of a generic estimate — it’s the difference between a payment you expected and one that surprises you.
What I tell buyers looking in Lake Country
Here’s the honest part. A lake view is worth a lot, but not a payment that keeps you up at night.
I’ve watched buyers stretch for lakefront and love it, and I’ve told others to buy the inland home a mile from the water and keep their weekends stress-free. Both can be right. What I won’t do is talk you into the top of your range just because the water’s pretty. Let’s find the number that fits your life, then go win the house.
The Lake Country communities
Each town here has its own feel. We’re building a local guide for each:
- Oconomowoc — three lakes and a historic downtown.
- Delafield — Nagawicka Lake and a walkable main street.
- Pewaukee — Pewaukee Lake, minutes from the freeway.
- Hartland — the Bark River and a growing downtown.
Frequently asked questions about buying a home in Lake Country
Do I need a jumbo loan to buy in Lake Country?
Sometimes. Homes above the conforming loan limit — often lakefront — need a jumbo loan. Plenty of inland homes still fit a conventional loan.
How much do I need to put down?
As little as 5% on a conventional loan; jumbo loans usually ask for more. Your down payment shapes both.
Can I finance a lake home as a second home?
Yes. Second-home financing exists — just tell me up front, because the guidelines differ from a primary residence.
Is buying in Lake Country competitive?
Yes, especially near the water. A strong pre-approval is your best tool for winning.
Key takeaways on buying a home in Lake Country
- Lake Country spans the lake towns of western Waukesha County — Oconomowoc, Delafield, Hartland, Pewaukee, and more.
- Prices run high; lakefront often pushes past the conforming limit into a jumbo loan.
- Conventional, jumbo, second-home, and construction loans all have a place here.
- A verified pre-approval is your edge in a fast, competitive market.
- Plan for higher property taxes on lake homes — they hit your escrow.
Thinking about a place on the water? Tell me the town and the price you’re eyeing, and I’ll tell you exactly what it takes — down payment, monthly payment, and whether you’re in conventional or jumbo territory. Same-day answers, 130+ lenders behind you, and you reach me directly.
Get my Lake Country number → calendly.com/adam-zeman/30min
Adam Zeman : Edge Home Finance
I’m Adam Zeman — a Wisconsin loan officer based minutes from Lake Country, and I answer my own phone.
Senior Loan Originator · NMLS #870441
Edge Home Finance, LLC · NMLS #891464 · Licensed in Wisconsin
(414) 975-2654 · azeman@edgehomefinance.com · adamzmortgageteam.com
YouTube: @Adamzmortgageteam · Reddit: u/azem4356 · Book a call: calendly.com/adam-zeman/30min
Read this next: How mortgage pre-approval works in Wisconsin
Educational only — not a rate quote. Loan programs and guidelines vary by lender and by borrower.