 If the only thing standing between you and a home feels like the pile of cash for a down payment, take heart — that hurdle is often smaller and more flexible than people realize. FHA loans are built for buyers who don’t have a fortune saved, and there are several honest ways to cover the upfront cost. I’m Adam Zeman, a licensed loan officer who works with Wisconsin first-time buyers every day, and FHA is one of the loans I set up most. Let me walk you through FHA down payment assistance — the real ways to cover the 3.5% — in plain dollars.
What is FHA down payment assistance?
In short, it’s any legitimate source of funds that helps you cover the FHA down payment and closing costs beyond your own savings. Because FHA only requires 3.5% down, the gap is usually modest — and several tools can fill it. So “assistance” here means gifts, seller and lender credits, and formal programs, used alone or stacked together. The result is that a thin savings account doesn’t have to keep you renting. You just need to know which levers to pull.
How much is the FHA down payment?
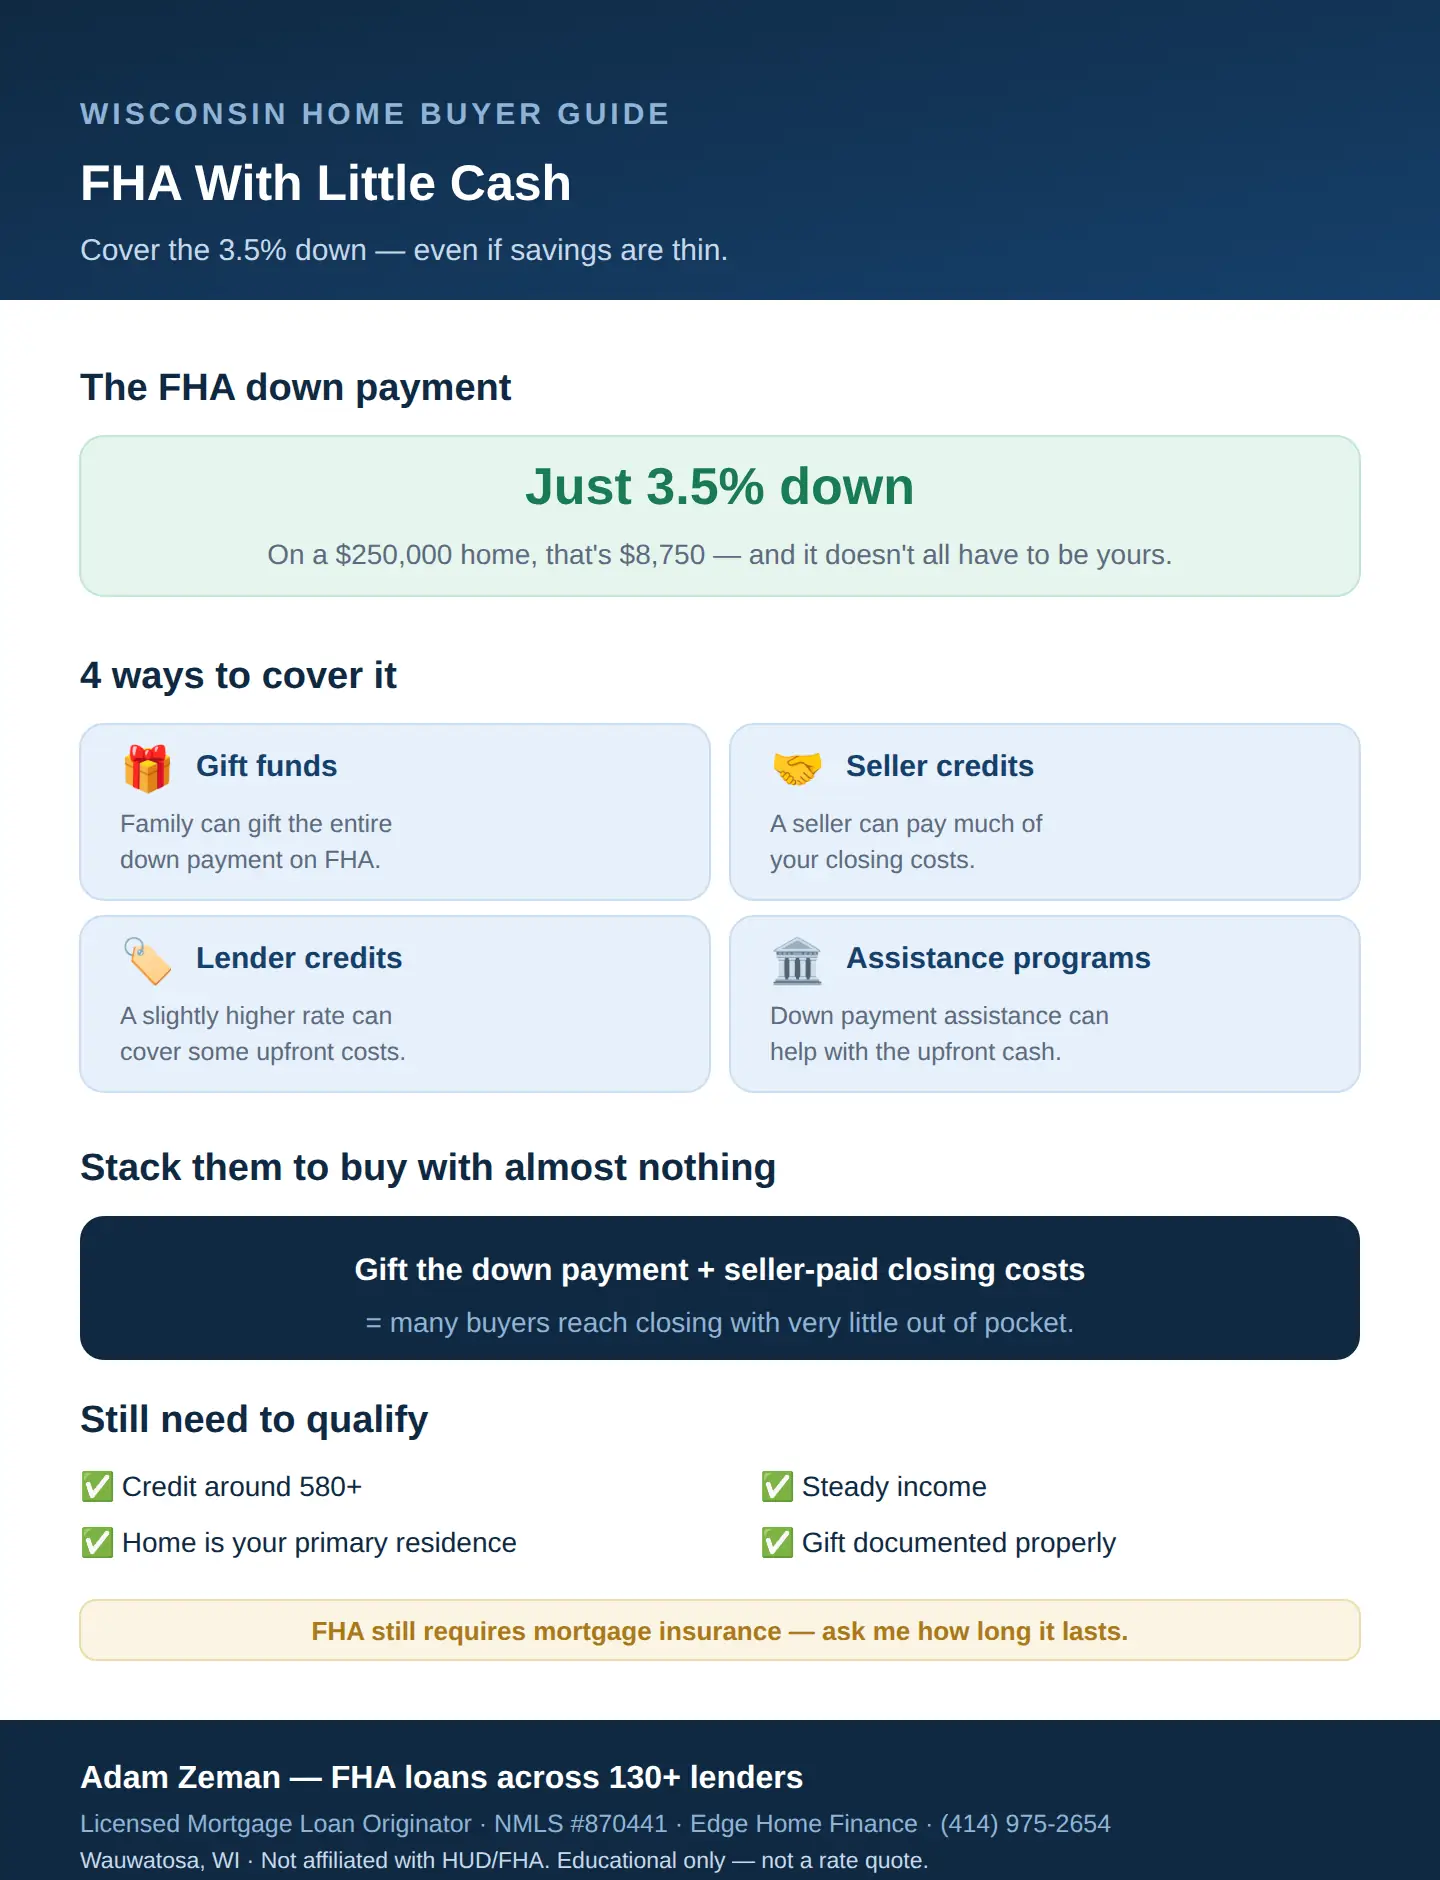
Just 3.5% of the purchase price, as long as your credit score is 580 or higher. On a $250,000 home, that’s $8,750 — compared with $50,000 for a 20% conventional down payment. So the number you’re actually trying to cover is far smaller than the old myth suggests. And here’s the key point: FHA allows that money to come from sources other than your own bank account, which is where assistance comes in.
What FHA down payment assistance options can cover it?
There are four main ways to reduce or cover your upfront cash, and because they stack, most buyers use more than one.
| Source | What it does |
|---|---|
| Gift funds | Family can gift the entire down payment on FHA |
| Seller credits | The seller can pay much of your closing costs |
| Lender credits | A slightly higher rate covers some upfront costs |
| Assistance programs | Down payment help toward the upfront cash |
So the goal is to combine these until the cash you personally bring is as small as possible.
Can gift funds cover the whole FHA down payment?
Yes, and this is the most common form of FHA down payment assistance. FHA specifically allows the entire 3.5% to come from a gift, usually from a family member. So a parent, grandparent, or close relative can hand you the down payment, and it fully counts. The one requirement is documentation: the gift needs a simple letter stating it’s not a loan, plus a paper trail showing the transfer. That’s a step I walk clients through so it goes smoothly.
How do seller and lender credits reduce your cash?
These two tackle closing costs rather than the down payment, but they matter just as much. A seller can agree to pay a portion of your closing costs, which lowers the total cash you owe at the table. Meanwhile, a lender credit trades a slightly higher rate for money toward those same costs. So if a gift covers your down payment and a seller credit covers your closing costs, you can genuinely get close to buying with very little of your own money.
Do you still have to qualify for the FHA loan?
Yes. FHA down payment assistance helps with the cash, but you still need to qualify for the loan itself. That means credit around 580 or higher, steady documented income, a debt-to-income ratio (DTI) within limits, and a home you’ll live in as your primary residence. Keep in mind FHA loans also carry mortgage insurance, which I’ll explain for your situation. For the full picture, see my guide to FHA loans in Wisconsin.
How do I use FHA down payment assistance in Wisconsin?
The honest answer is that it starts with a conversation about your specific situation, since the right mix of gifts, credits, and programs depends on your numbers and the home. That’s the part I handle — I map out exactly how to cover your upfront cost and shop your loan across 130+ lenders so you keep as much cash in your pocket as possible.
What I see in the field
In fact, the buyers I work with are usually surprised by how little of the 3.5% has to come from their own account. For example, on a $250,000 FHA purchase that down payment is $8,750 — and between a family gift, a seller credit toward closing costs, and a lender credit, I’ve had first-time buyers reach the closing table with only a few hundred dollars of their own in the deal. Still, the catch is documentation: assistance has to be sourced and papered correctly, or underwriting stalls. So line it up early, and it stays smooth. If you want to see what your own number looks like, start with a pre-approval so we’re working from real figures.
Frequently asked questions
Can the FHA down payment be a gift? Yes. FHA allows the entire 3.5% down payment to come from a documented gift, usually from family. How much do I really need for an FHA loan? Just 3.5% down, or $8,750 on a $250,000 home — and gifts, seller credits, and assistance can cover much of it. Can the seller pay my closing costs on FHA? Yes, up to allowed limits. Seller credits toward closing costs can meaningfully lower your cash to close. What are lender credits? They’re money the lender puts toward your costs in exchange for a slightly higher rate — useful when cash is tight. Do I still pay FHA mortgage insurance? Yes. FHA loans carry mortgage insurance regardless of how you fund the down payment; I’ll explain how long it lasts. What credit score do I need? 580 or higher for 3.5% down. Some lenders set higher minimums, so it pays to shop. Can I combine gift funds and seller credits? Yes. Stacking a gift for the down payment with seller-paid closing costs is a common, powerful combination. Does the gift have to be documented? Yes. A short gift letter and a clear paper trail are required, which I help you handle.
Key takeaways
- FHA down payment assistance helps cover the 3.5% ($8,750 on a $250,000 home) beyond your own savings.
- Gift funds can cover the entire FHA down payment, usually from a family member.
- Seller credits and lender credits reduce your closing costs, lowering your total cash.
- Also explore down payment assistance programs, and stack these sources together.
- You still qualify normally — around 580 credit, steady income, primary residence — and FHA has mortgage insurance.
Want to cover your down payment?
Tell me your situation and I’ll map out exactly how to cover your upfront cost across 130+ lenders. Grab a 15-minute call on my calendar, or call or text me at (414) 975-2654.
Adam Zeman : Edge Home Finance
Senior Loan Originator
Edge Home Finance, LLC | NMLS #870441 | Company NMLS #891464
Direct: (414) 975-2654 | Email: azeman@edgehomefinance.com
Website: adamzmortgageteam.com | Schedule a call: calendly.com/adam-zeman/30min
Educational only — not a rate quote. Down-payment and program guidelines vary by lender and by borrower, mortgage insurance may apply, and not all borrowers will qualify. Edge Home Finance, LLC is a private broker, not affiliated with HUD, the FHA, or any government agency.
Adam Zeman — Licensed Mortgage Loan Originator, NMLS #870441 — Edge Home Finance, LLC, Company NMLS #891464 — 11220 W Burleigh St, Suite 174, Wauwatosa, WI 53222 — (414) 975-2654 — Book: calendly.com/adam-zeman/30min. Edge Home Finance, LLC is a private mortgage brokerage and is not affiliated with HUD, the FHA, or any government agency. Educational information only, not a rate quote or commitment to lend. Assistance availability, FHA guidelines, and credit requirements vary by lender and by borrower. All loans subject to credit approval and underwriting. Equal Housing Opportunity.